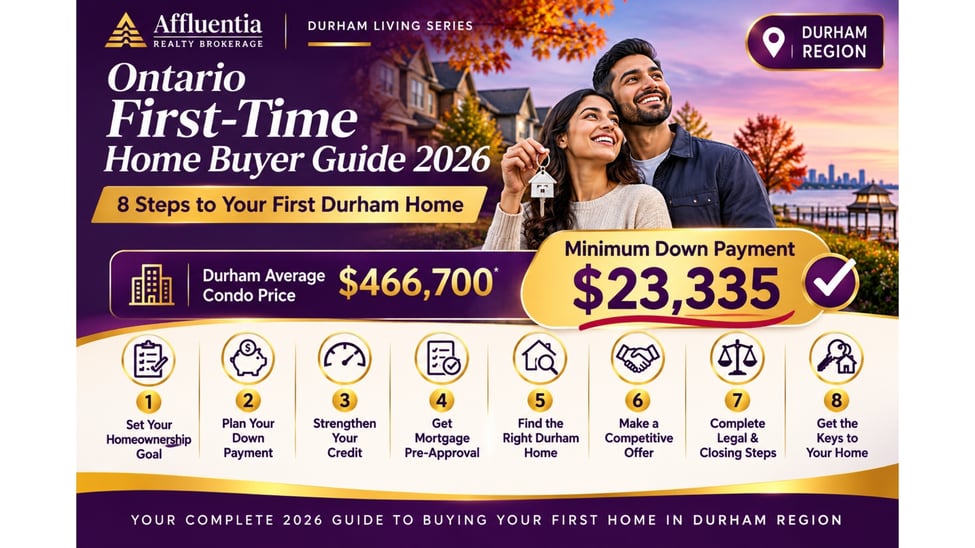
Buying your first home is one of the biggest financial moves you'll ever make, and in Ontario it comes with its own set of rules, programs and paperwork. As a former banker turned Broker of Record, I like to tell first-time buyers something simple: your first home is property number one. Get the foundation right and every move after it gets easier. 🏡
This Ontario first-time home buyer guide walks you through the whole journey, step by step, with real numbers from Durham Region so you can see what each step looks like in Ajax, Whitby, Oshawa, Clarington and Pickering today.
Step 1: Know where the Durham market stands right now
Before you set a budget, it helps to know what homes are actually selling for. According to TRREB's October 2026 Market Watch, Durham Region recorded 589 sales at an average price of $793,024 (median $740,000). Homes took an average of 29 days to sell and went for about 98% of their list price, with 2,619 active listings on the market. In plain English: buyers have more choice and more time than they did a few years ago.
Average sale price by Durham town, October 2026 (all home types)
Source: TRREB Market Watch, October 2026
By home type, Durham's October averages were $466,698 for a condo apartment, $524,852 for a condo townhouse, $617,652 for a semi-detached and $875,260 for a detached home. Many of my first-time buyers start in Oshawa or Courtice, where entry prices are lower, then work toward Whitby, Ajax or Brooklin on their second move.
Step 2: Get clear on your down payment
In Canada, the minimum down payment depends on the purchase price:
- $500,000 or less: 5% of the price
- $500,000 to under $1.5 million: 5% of the first $500,000, plus 10% of the portion above $500,000
- $1.5 million or more: 20%
Since December 15, 2024, insured (high-ratio) mortgages are available on homes up to $1.5 million, and first-time buyers can choose a 30-year amortization on an insured mortgage, which lowers the monthly payment. If you put down less than 20%, you'll need mortgage default insurance; the premium is usually added to your mortgage, but in Ontario the sales tax on that premium is due in cash at closing.
Minimum down payment at Durham's average prices, October 2026
Source: TRREB Market Watch, October 2026 (average prices); Government of Canada minimum down payment rules. Calculated by Affluentia Realty.
Step 3: Use the tax-smart savings tools
Two federal programs can do a lot of the heavy lifting on your down payment 💰:
- First Home Savings Account (FHSA): contribute up to $8,000 a year, to a lifetime limit of $40,000. Contributions are tax-deductible and a qualifying withdrawal to buy your first home is tax-free.
- RRSP Home Buyers' Plan (HBP): withdraw up to $60,000 from your RRSPs and repay it over 15 years. For first withdrawals made from 2022 through 2028, repayments don't start until the fifth year after the withdrawal.
You can use both for the same home if you meet the conditions for each. For a couple, that can add up quickly. I covered these and the other rebates in detail in my post First-Time Home Buyer Programs in Ontario (2026), so here I'll just say: talk to your accountant early, because timing your contributions matters.
Step 4: Get pre-approved (and understand the stress test)
A mortgage pre-approval tells you what a lender is willing to lend and holds a rate for a period of time. Your lender will look at your income, debts, credit history and down payment, and will qualify you at a higher "stress test" rate than your actual contract rate. That's why your approval may come in lower than you expected. 📋
From my banking days, a few tips:
- Don't open new credit or finance a car while you're shopping for a home.
- Have your down payment sitting in your own account, with a clear paper trail.
- A pre-approval is not a final approval. The lender still has to approve the specific property.
Step 5: Budget for closing costs, not just the price
Closing costs catch many first-time buyers off guard. The biggest one is Ontario's land transfer tax, but first-time buyers can get a refund of up to $4,000. Here's what that looks like at Durham's October averages:
| Home (Oct 2026 avg) | Price | Ontario LTT | After $4,000 refund |
|---|---|---|---|
| Durham condo apartment | $466,698 | $5,809 | $1,809 |
| Oshawa (all types) | $653,466 | $9,544 | $5,544 |
| Clarington (all types) | $742,452 | $11,324 | $7,324 |
| Whitby (all types) | $876,275 | $14,000 | $10,000 |
To qualify for the Ontario refund, you must be at least 18, a Canadian citizen or permanent resident, never have owned a home anywhere in the world, and move in within nine months. Durham buyers don't pay a municipal land transfer tax; that one applies in the City of Toronto. Add legal fees, title insurance, a home inspection and moving costs, and plan your cushion accordingly. My Buying a Home in Durham Region: 2026 Closing Costs Guide breaks all of this down.
Buying brand new? Eligible first-time buyers can apply for the federal First-Time Home Buyers' GST/HST Rebate of up to $50,000 on a newly built home (agreements signed on or after March 20, 2025), with full criteria on the CRA website.
Step 6: Shop with a plan, not just a wish list
Now the fun part. 🔑 Before we book showings, I ask my buyers three questions: Where do you need to commute? What must the home have? What would you happily trade off? A couple working in Toronto might favour Pickering or Ajax near the GO line, while a family wanting more space for the money might look at Bowmanville or Courtice. Condo townhouses in Oshawa and Whitby are a popular middle ground for first-timers.
Look at condo fees, property taxes and the age of big-ticket items (roof, furnace, windows), not just the listing photos.
Step 7: Make a smart offer
With homes in Durham selling at about 98% of list price on average in October, there is often room to negotiate, and protecting yourself with conditions is realistic again. Common conditions include:
- Financing, so you aren't committed until the lender approves the property
- Home inspection
- Status certificate review by your lawyer, for condos
Your deposit is usually due within 24 hours of acceptance, so have it ready in your account.
Step 8: Firm up, close and get your keys
Once your conditions are met and the deal is firm, your real estate lawyer takes over the legal side: title search, mortgage documents, land transfer tax and your first-time buyer refund. You'll sign at the lawyer's office a few days before closing, bring your balance of down payment and closing costs, and on closing day you get the keys. 🎉 Then set a calendar reminder to apply for any rebate you didn't claim at closing.
How we approach this: The Affluentia Way
Every client I work with goes through the same four-stage plan we call The Affluentia Way:
- Clarity: we map your numbers, from down payment and FHSA/HBP savings to closing costs and monthly payment, so you know your true budget before you fall in love with a house.
- Positioning: we line up your pre-approval, deposit and target neighbourhoods so you're ready to move when the right home appears.
- Execution: we find the home, negotiate a strong offer with the right conditions, and coordinate with your lender and lawyer through closing.
- Expansion: we treat your first home as property number one and plan how its equity can help with your next move or first investment.
Ready to buy your first home in Durham?
If you're thinking about buying in the next 6 to 18 months, let's sit down and map out your plan. You can book a free 30-minute call here or call me at 647.282.8078. I'm also hosting a first-time buyer seminar on Thursday, November 26, 2026 at 5:30 PM at our Oshawa office. Reach out to save your seat. 😊
Neeraj Khanna, Broker of Record, Affluentia Realty
This article is general information only and is not tax, legal, mortgage or financial advice. Program rules and market figures change; please confirm details with your accountant, lawyer and lender before making decisions.