If you're renting in Ajax, Whitby or Oshawa and dreaming about your first set of keys, there's one account I bring up in almost every first-time buyer conversation: the First Home Savings Account (FHSA). 🏡 Back in my banking days I watched people leave a lot of money on the table simply because nobody explained how these registered accounts work. So in this guide I'll walk you through the FHSA in plain language: who qualifies, how much you can put in, how the tax break works, how to take the money out for a Durham home, and how it fits with the RRSP Home Buyers' Plan. I always say your first home is property number one, and the FHSA is one of the best tools for getting there.
What is the FHSA?
The FHSA is a registered account from the federal government that lets first-time buyers save for a qualifying home in Canada, tax-free, up to set limits. The Canada Revenue Agency (CRA) describes it as combining two big advantages:
- Going in: contributions are generally tax-deductible, much like an RRSP, so they can lower the tax you pay.
- Coming out: a qualifying withdrawal to buy your first home is tax-free, much like a TFSA. Investment growth inside the account comes out tax-free too.
That "deduction in, tax-free out" combination is what makes the FHSA so powerful. No other account gives you both for a home purchase.
Who can open an FHSA?
According to the CRA, you must meet all three of these conditions when you open the account:
- You're at least 18 years old.
- You're a resident of Canada.
- You're a first-time home buyer. For the FHSA, that means that at any time in the current calendar year before you open the account, or in the previous four calendar years, you didn't live in a home as your principal residence that you, or your current spouse or common-law partner, owned or jointly owned.
That last point surprises people. If you owned a condo years ago and have rented since then, you may qualify again. On the other hand, if your spouse owns the home you both live in today, you likely don't. When in doubt, check with the CRA or your accountant before opening.
How much can you contribute?
Here are the CRA limits in plain numbers:
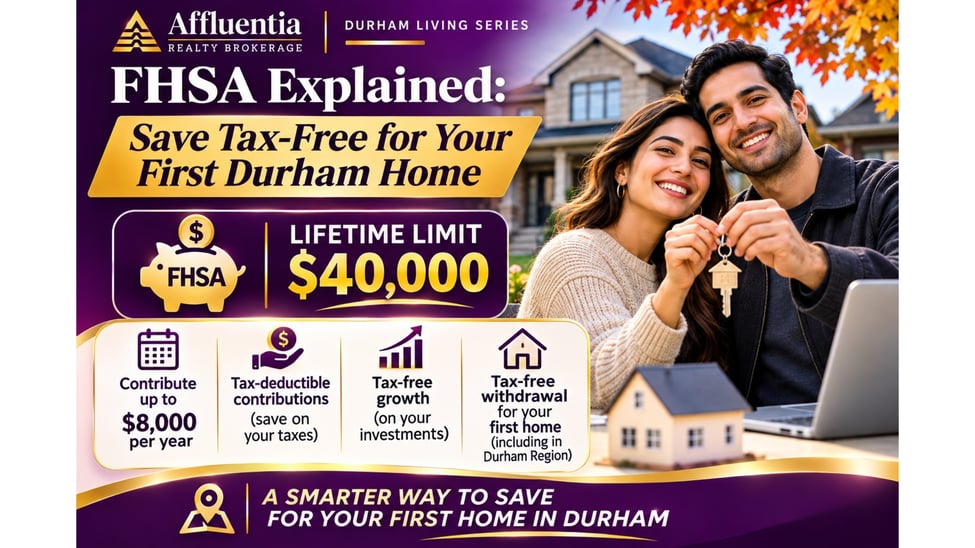
- $8,000 of participation room in the year you open your first FHSA.
- $40,000 lifetime limit.
- Unused room carries forward, but the carry-forward is capped at $8,000. So the most you can ever contribute in one year is $16,000.
- Room starts when you open the account, not when you turn 18. Opening early (even with $0 in it) starts the clock on your room.
- Over-contributing costs you a tax of 1% per month on the highest excess amount in that month, so track your room carefully.
| FHSA rule (CRA) | What it means for you |
|---|---|
| Annual room: $8,000 | You can put in up to $8,000 a year, plus up to $8,000 of unused room carried forward |
| Lifetime limit: $40,000 | Five full years of contributions fills the account (growth doesn't count against it) |
| Contributions are deductible | You can claim the deduction now or carry it forward to a higher-income year |
| Qualifying withdrawal is tax-free | Your contributions and growth can go to your down payment with no tax |
| Account time limit | Ends Dec 31 of the year of your 15th anniversary, the year you turn 71, or the year after your first qualifying withdrawal, whichever comes first |
| Didn't buy? | You can transfer the funds to your RRSP or RRIF tax-free, without using RRSP room |
That last row is a big reason I tell almost every eligible renter to at least consider an FHSA. If life changes and you never buy, the money can move into your RRSP without using up RRSP contribution room. Most of the risk is gone. 👍
How the tax deduction works (a simple example)
Say you earn a salary and contribute $8,000 to your FHSA this year. That $8,000 comes off your taxable income. How much you actually save depends on your tax bracket. As a simple illustration only, at a 30% marginal rate the deduction would be worth roughly $2,400 in tax. One smart option is to put that refund straight back into your FHSA or set it aside for closing costs.
Something people often miss: you don't have to claim the deduction in the year you contribute. If you expect a raise, a promotion or a new job in a couple of years, you can carry the deduction forward and claim it when your tax rate is higher. That's a question for your accountant, but it's worth asking.
What $40,000 means in Durham Region
Let's bring this back to real Durham numbers. In Canada, the minimum down payment is 5% of the first $500,000 of the price plus 10% of the portion between $500,000 and $1.5 million (Financial Consumer Agency of Canada). Here's what that works out to at the October 2026 average sale prices reported in TRREB's Market Watch:
Minimum down payment at the average Durham sale price (Oct 2026)
Source: TRREB Market Watch average prices (all home types), October 2026; minimum down payment rules from the Financial Consumer Agency of Canada. Calculated by Affluentia Realty.
Look at Oshawa: a fully funded $40,000 FHSA covers about 99% of the minimum down payment on an average-priced Oshawa home ($653,466). Across Durham as a whole (average $793,024), one full FHSA covers roughly 74% of the minimum. And for a couple who each have an FHSA, $80,000 in contributions would clear the minimum down payment in every town above, before any investment growth. 💡
Keep in mind these are averages across all home types. A condo townhouse in Oshawa or Courtice will need less, and a detached home in Ajax or Brooklin will need more. Closing costs come on top, so I always build those into the plan too.
FHSA + RRSP Home Buyers' Plan: using both
Here's the strategy that gets the most out of the rules. The CRA confirms you can use the FHSA and the RRSP Home Buyers' Plan (HBP) for the same home, as long as you meet the conditions for each. The HBP lets you borrow up to $60,000 from your RRSP for a first home. The main difference: HBP money has to be paid back to your RRSP over 15 years, while a qualifying FHSA withdrawal never has to be repaid. Under the current CRA rules, if your first HBP withdrawal is between 2022 and 2028, repayments start in the fifth year after the withdrawal.
Maximum registered savings you can put toward a first home
Source: Canada Revenue Agency (FHSA lifetime limit and HBP withdrawal limit), November 2026. FHSA amounts are contributions only, before investment growth.
Of course, very few buyers will max out both. The point is that the system has room for you, and the earlier you start, the more of it you can use.
How to withdraw your FHSA for a Durham home
When you've found your home, say a semi in Oshawa's Eastdale or a townhouse near the Whitby GO, the CRA requires that, at the time of the withdrawal:
- You're still a first-time home buyer (for withdrawals, the 30 days just before the withdrawal don't count against you).
- You have a written agreement to buy or build a qualifying home, with closing (or completion) before October 1 of the year after the withdrawal.
- You haven't bought the home more than 30 days before the withdrawal.
- You plan to live in it as your principal residence within one year.
- You complete Form RC725 and give it to your FHSA provider.
A practical tip from experience: talk to your bank or brokerage about the withdrawal as soon as your offer is firm. Investments may need to be sold, and you want the cash ready in your lawyer's trust account well before closing day. A withdrawal that doesn't meet the rules is taxable, which is the last surprise you want. 😅
Common FHSA mistakes I see
- Waiting to open it. Room only builds once the account exists, so even a $0 account opened this year is worth having.
- Over-contributing across multiple FHSAs. The limits are per person, not per account.
- Leaving it all in cash. If your purchase is years away, ask an advisor about investment options that fit your timeline.
- Forgetting the paperwork. You report FHSA activity on your tax return (Schedule 15 in the year you open), even if you didn't contribute.
For the bigger picture, see my posts First-Time Home Buyer Programs in Ontario, Ontario First-Time Home Buyer Guide 2026 and Buying a Home in Durham Region: 2026 Closing Costs Guide.
How we approach this: The Affluentia Way
Every client I work with goes through the same four-stage plan we call The Affluentia Way.
- Clarity: We map out your numbers together: your FHSA and RRSP balances, your savings pace, your target town and the down payment and closing costs you'll actually need.
- Positioning: We line up your pre-approval and the timing of your FHSA and HBP withdrawals so your money is ready when the right home in Ajax, Whitby or Oshawa comes up.
- Execution: We negotiate the purchase, coordinate with your lender, lawyer and FHSA provider, and get you to closing day.
- Expansion: Once you're in, we look at how your first home can become the foundation for property number two and a growing portfolio.
Let's plan your first home together
If you want to know how far your FHSA can take you in Durham, I'd love to help. ☕ Book a free 30-minute call or call me at 647.282.8078. You're also invited to my First-Time Buyer Seminar on Thursday, November 26, 2026 at 5:30 PM at our Oshawa office, where we'll cover the FHSA, the Home Buyers' Plan and the full buying process step by step.
Neeraj Khanna, Broker of Record, Affluentia Realty
This article is general information only and is not tax, legal or financial advice. FHSA and Home Buyers' Plan rules can change; please confirm your situation with the CRA, a qualified accountant or financial advisor, and a real estate lawyer before acting.